Author

admin

Browsing

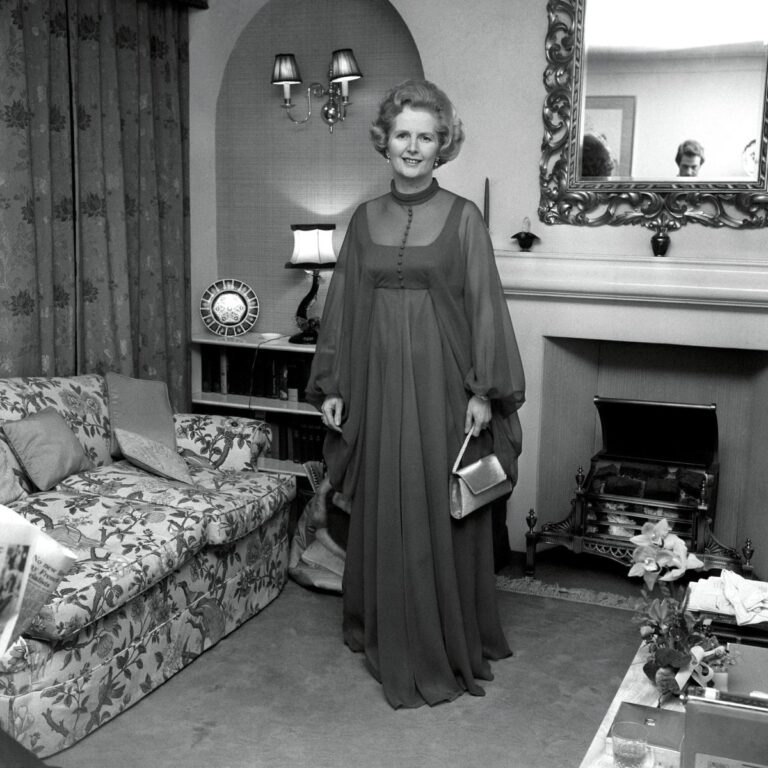
Margaret Thatcher in her chiffon gown on 1 February 1976 (PA Images/Alamy)

Robert Hutton


4 min read30 October

Fifty years ago, the female leader of the Tory opposition was about to celebrate a newly minted moniker, a gift from Russia

We don’t, sadly, know what was on the menu 50 years ago for the Finchley Conservatives Dinner Dance. Although we’ve all been to a few things like this, and we can be pretty confident that it wasn’t roasted swan in truffle sauce. It was probably chicken. It’s usually chicken. And it wasn’t like it was going to matter. No one was ever going to remember the Finchley Conservatives Dinner Dance of 1976.

Except that they would because of the after-dinner speech made by the local Member of Parliament, Margaret Thatcher. She’d been leader of the opposition for just under a year and was still laying out the direction in which she wanted to take her party. A couple of weeks earlier, she’d made a foray into foreign policy, calling for the country to take a more confrontational stance to the Soviet Union, which was, she said, “bent on world dominance”.

That speech got a big reaction in Britain, but also from Moscow, with the Red Army newspaper, Red Star, provoked into making what was intended as an insulting comparison with Otto von Bismarck, the “Iron Chancellor” of Germany. Mrs Thatcher, said the paper, was “the Iron Lady”. Bob Evans, the Moscow bureau chief of Reuters, spotted the headline and reported it.

A few months earlier, he’d written up a Russian propaganda poster that portrayed the Tory leader as a “Cold War witch”. She hadn’t liked that, but this was different. Thatcher gave her reply to the Finchley Tories. “I stand before you tonight in my Red Star chiffon evening gown,” she said, to laughter and applause – Thatcher wasn’t a natural humourist, but she was among friends that evening – “my face softly made up and my fair hair gently waved, the Iron Lady of the Western world.”

She continued: “Yes, I am an Iron Lady. After all, it wasn’t a bad thing to be an Iron Duke. Yes, if that’s how they wish to interpret my defence of values and freedoms fundamental to our way of life!”

“Yes, I am an Iron Lady. After all, it wasn’t a bad thing to be an Iron Duke.”

There’s a long tradition of insults being adopted by their targets as badges, from the Quakers to the Suffragettes to the Barmy Army. Even “prime minister”, another title that Thatcher would make her own, began life as an 18th-century term of abuse for a royal favourite.

But none has backfired quite so spectacularly as Red Star’s. Thatcher hoped to be Britain’s first female prime minister in an age when some questioned whether a woman was tough enough to do the job. Now the nation’s enemies were suggesting she was too tough for their taste. It couldn’t have gone better if the Tories had scripted the insult for them. Thatcher herself had subtly reinterpreted it as a reference not to the suspiciously foreign Bismarck but to the Iron Duke of Wellington, the man who beat Napoleon.
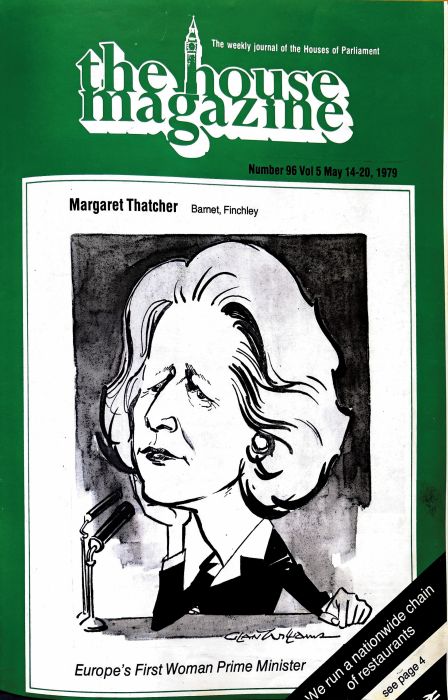
Thatcher House magazine

The rest of that speech in Finchley wasn’t a major one, but reading it half a century later, it offers a good guide to Thatcher’s decade in power: abroad, the desire to confront communism; at home, a belief that the public exercised more control over business through ownership of shares and competition than it ever could through nationalisation, and that people should be free to buy their council homes and choose their children’s state schools.

As a mark of their affection that evening, Thatcher’s association presented her with an inscribed champagne ice bucket. Red Star had given her something far more valuable: a nickname that would be worn as a badge of pride for the rest of her life. 
Vonovia share price continued its strong sell-off this week as the company published a surprise report, lowering its guidance for the year. It dropped to a low of €15.25 before paring back some of these losses to the current €16.24. It is now hovering near its lowest level since 2014 after falling by 73% from its highest point in 2022.

Vonovia, the biggest landlord in Germany, is facing major challenges. One of these risks is a new law in Berlin that allows authorities to seize houses in a bid to lower prices.

The proposal is for authorities to buy these houses from their current owners and then lower rents that people pay. In this case, the estimate is that the government will spend about €100,000 per apartment, much lower than their current values. 

As a result, Vonovia is expected to lose about €8.4 billion as 120,000 of its apartments are brought into public ownership. Estimates are that the company’s properties are valued at about €130,000.

Still, it is unclear whether this will happen, as Vonovia and other companies in the industry have vowed to sue. The national government, under Friedrich Merz, have also urged against seizing these properties. He argues that it will be illegal and make it hard to attract investors in the real estate sector. 

Vonovia shares also dropped after the company published a statement warning about its business as interest rates and financing costs continue rising. The company blamed the crisis to the US-Iran war that led to higher inflation in Germany and other countries.

In the aftermath, interest rates and bond yields have continued rising. The European Central Bank (ECB) hiked interest rates in September and analysts now expect it to deliver more hikes in the coming months. 

As a result, the company’s re-offer yield of its eight-year unsecured bonds jumped by 140 basis points. Its bonds that are maturing in 2032 are yielding 6.71%, much higher than the year-to-date low of 5.2%.

Vonovia’s preliminary nine-month results for the first nine months of the year showed that its adjusted EBITDA will be €2.19 billion, up from €2.118 billion in the same period last year. In the statement, the management said:

“Vonovia remains committed to deleveraging and will continue its disposal program as a matter of top priority. Its deleveraging targets remain unchanged: net debt/EBITDA is expected to improve to below 12x and the interest coverage ratio to remain comfortably above 3x by the end of 2028.”

Vonovia stock chart | Source: TradingView

The daily chart shows that Vonovia shares have slumped in the past few years, moving from a high of €33.93 in 2024 to the current 16.28. It has slowly formed an inverted cup-and-handle pattern whose lower side is at €15.25. This pattern often leads to more continuation.

The stock has slumped below the 50-week and 100-week Exponential Moving Averages (EMA). Remaining below that level is a sign that investors remain in control. Therefore, the stock will likely continue falling, potentially to the key support level of €13. 

Gold price continued its downward trend, reaching its lowest level in months as demand waned after the hawkish Federal Reserve interest rate decision. It dropped to $3,925, down modestly from the August high of $4,700. This sell-off may continue as President Donald Trump prepares to escalate his attacks against Iran.

Visit Site

Gold faces fresh pressure as higher-rate expectations weigh on demand.

51% of retail investor accounts lose money when trading CFDs with this provider.

The daily chart shows that gold has come under pressure in the past few weeks, moving from a high of $4,700 in September to a low of $3,958. It has now crossed the important support level of $4,000 as it continued its series of lower lows and lower highs.

Gold formed a death cross pattern, which forms when the 50-day moving average crosses the 200-day moving average. This pattern often leads to more downside. At the same time, the Relative Strength Index (RSI) has dropped from the overbought level of 72.5

Therefore, these patterns suggest that gold may continue falling, potentially to the next key support level of $3,900. The risk, however, is that gold has formed a triple-bottom pattern whose neckline is at $4,700. This pattern means that sellers may attempt to push it higher in the near term. 

Gold price chart | Source: TradingView

The ongoing gold price rally is happening as crude oil rally continues. Brent, the international benchmark, rose to $113, while the West Texas Intermediate (WTI) moved to $104. Higher oil prices mean that inflation will remain stubbornly high in the foreseeable future. 

Oil prices will likely continue rising after the US midterm elections in which Democrats are expected to win the House of Representatives and the Senate. President Donald Trump has warned that he will launch a short attack on Iran in a bid to put pressure on the IRGC to talk. Iran has warned that it will escalate if the US attacks it. 

The most recent data showed that the headline consumer price index (CPI) rose 3.7% last month, while the core figure moved to 2.7%. Similarly, the headline and core personal consumption expenditure (PCE) remained above the 2% target during the month. 

These numbers mean that the Federal Reserve will likely maintain higher interest rates for longer. In its last decision this week, the bank decided to leave rates unchanged between 3.75% and 4%. Two officials – Beth Hammack and Lisa Cook – voted to hike interest rates.

In his statement after the Fed decision, Governor Kevin Warsh maintained that inflation remained stubbornly high and that the Fed will do whatever it takes to bring it down. As a result, analysts expect the bank to hike interest rates in its December meeting. 

Gold tends to underperform the market when the Fed is hiking interest rates and when bond yields are at an elevated level.

Opening your first investing account is an exciting milestone. It marks the beginning of your journey toward financial independence, wealth creation, and potentially achieving long-term financial goals. With the convenience of online brokerages, getting started has never been easier. But before you click “apply” and start buying stocks, there are several important considerations that could make a significant difference to your investing experience.

The biggest mistake beginners can make is focusing exclusively on potential returns while overlooking the risks, costs, and account choices involved. Here’s what you should know first.

Source: Getty Images

Understand the risks before seeking returns

Investing in stocks offers the potential for attractive long-term returns, but there are no guarantees. When you purchase an individual company’s shares, you become a part-owner of that business. If the company fails, your investment could lose most or even all its value.

That’s why stock selection matters. Look for businesses with durable competitive advantages, sustainable revenue and earnings growth, capable management teams, and strong balance sheets. Financial strength can help companies withstand economic downturns and navigate challenging market conditions.

Valuation matters just as much. Even an excellent business can become a poor investment if you pay too much for its shares. Buying at an excessive valuation can limit future returns, even when the company continues growing. Remember, investing is not simply about finding great companies; it’s about buying them at reasonable prices.

Consider Brookfield Asset Management (TSX: BAM), for example. Its global alternative asset management business offers exposure to infrastructure, renewable power, real estate, and private equity. Its established operations and long-term investment opportunities make it a good business to research. 

Its growth drivers include fee-bearing capital expansion to US$672 billion at the end of the second quarter (Q2) – up 19% year over year, record-setting fundraising (US$77 billion in Q2), and integration of strategic platforms (e.g., Oaktree for its global credit platform, spanning real asset, asset-backed, and opportunistic credit). 

Valuation-wise, at about $67 per share at writing, BAM trades at a discount of 10–13% to the analyst consensus price target and offers a dividend yield of 4.2% – a dividend that grew about 15% per year recently. So, it may be a reasonable buy for income and long-term price-appreciation potential within a diversified stock portfolio.

Choose the right investing account

Canadian investors have several account options, and choosing the right one can significantly affect after-tax returns.

A Tax-Free Savings Account (TFSA) allows eligible investments to grow and generate income tax-free, with qualifying withdrawals also tax-free. A Registered Retirement Savings Plan (RRSP) generally provides a tax deduction for eligible contributions, while investments grow tax-deferred until withdrawal. A First Home Savings Account (FHSA) combines tax-deductible contributions with tax-free qualifying withdrawals for a first home purchase.

Each account has contribution limits, eligibility requirements, and withdrawal rules. Understand these before contributing. Overcontributing can trigger penalties, so keep track of your contributions.

Consider fees, diversification, and your time horizon

Not all investing platforms are created equal. Compare brokerage commissions, foreign exchange fees, account administration charges, and other costs before opening an account. Even seemingly small fees can eat into your returns over time.

More importantly, avoid putting all your money into one or two stocks. Diversification across companies, industries, and asset classes can reduce the impact of any single investment performing poorly. Beginners may find low-cost, diversified exchange-traded funds (ETFs) a practical starting point.

Also, invest according to your time horizon and risk tolerance. Money needed within a year shouldn’t be invested in a stock market that’s inherently volatile. Only consider investing in stocks for money you don’t need for at least the next three to five years.

The bottom line

Opening your first investing account is about building a solid foundation for long-term financial success. Understand the risks, choose an appropriate Canadian registered account, compare brokerage fees, and diversify. Most importantly, invest patiently and avoid chasing quick gains. A thoughtful start can help turn your first investment into the beginning of a disciplined wealth-building journey.

Home Depot is making a significant move to lure customers into its stores after recently seeing weak sales growth.

The home-improvement chain revealed in its most recent earnings report that its U.S. comparable sales increased 1.3% year over year in the second quarter of 2026. 

Foot traffic in its stores also slipped during the quarter, as recent Placer.ai data revealed that average visits per Home Depot location declined 0.6% year over year. 

“Consumer uncertainty and housing affordability continue to pressure demand for larger home improvement projects,” a trend that is impacting sales, Home Depot Chief Financial Officer Richard McPhail said on an earnings call in August. 

“We have a lot of volatility,” he said. “We have unplanned cost pressure that is significant in the market, and we have frozen housing conditions. With all of that, we are focused on controlling what we can control.”

Home Depot announces new customer discounts ahead of Black Friday

As Home Depot faces significant headwinds, it has launched steep discounts and generous deals for the holiday shopping season.  

The company has announced in a recent press release that its Black Friday Savings Event, which offers deals on home improvement essentials, major appliances, power tools, and holiday décor in stores and online, officially begins on Nov. 5 and ends on Nov. 25. 

During the event, Home Depot is offering customers buy-one-get-one-free (BOGO) deals on select power tools. For instance, customers who purchase an eligible tool or battery kit from brands such as DEWALT, Milwaukee, and RYOBI can receive a select power tool for free. 

The home-improvement chain is also offering significant discounts on major appliances. 

For example, Home Depot states that customers can “save up to an extra $500 on qualifying refrigeration purchases of $2,498 or more, up to $300 on laundry purchases of $1,698 or more, up to $300 on cooking purchases of $1,498 or more and up to $150 on dishwasher purchases of $798 or more, with a maximum discount of $1,250.”

Read more: Lowe’s launches a new service as it works to win back customers

Home Depot is also launching deals on Hubspace smart home products, tool kits, and accessories during the event.

For holiday decor, the company is offering savings on indoor and outdoor items, including 100-count LED string lights for $5.98, select 3.5-foot LED pre-lit inflatables for $19.98, and 6.5-foot LED pre-lit artificial Christmas trees for $49.98.

The Black Friday deals from Home Depot come as it faces heightened competition from Lowe’s, its top rival. Lowe’s kicked off its Black Friday sales early on Oct. 29, and they are set to last for four weeks. 

Just like Home Depot, Lowe’s is offering discounts on holiday décor, tools, appliances, and outdoor power equipment, with special deals featuring free products with select purchases from major tool brands.

Lowe’s is taking it a step further this year by expanding its annual 10 Days of Deals to 12 Days of Deals, which begins on Nov. 16. It is also launching its biggest Black Friday savings during Thanksgiving week. 

Home Depot is launching generous Black Friday deals as it struggles to dramatically increase its U.S. comparable sales.

jetcityimage / Getty Images

Home Depot faces mounting challenges heading into the holidays

Home Depot is also making a major push to attract holiday shoppers at a time when many are limiting their spending due to economic pressures.

A recent survey by Thrivent found that 52% of Americans expect the current economic environment to affect their holiday spending at least somewhat. Approximately 72% said inflation is negatively impacting their household finances, while 71% said the same about gas prices.

Amid these challenges, 66% of Americans said they will purchase fewer gifts during the holiday season this year, up from 56% in 2025, while 46% plan to buy for fewer people, up from 37%. Also, 51% plan to purchase less expensive gifts while holiday shopping.

More Retail:

  • Ross Stores customers will soon feel a notable change in stores
  • Publix struggles to reverse concerning customer behavior
  • Home Depot faces uphill battle amid a growing customer problem

In an interview with Retail TouchPoints in August, Neil Saunders, a retail analyst at GlobalData, said there will be some winners and losers during the holiday season as consumers change their spending habits. 

“2026 will be a solid enough holiday season and consumers will come out and spend,” said Saunders. “That said, under the headline, spending will be selective and consumers will be very discerning about what they buy and where they buy it. This will mean results will be polarized. Some retailers will see good gains and others won’t.”

For Home Depot and other home-improvement chains, these consumer trends may be exacerbated by continued housing market headwinds. 

According to Freddie Mac data, the average 30-year fixed mortgage rate reached 6.86% in September, up from 6.67% in August and 6.35% one year ago. 

As rates went up, existing-home sales decreased 2.2% year over year in September, recent data from the National Association of Realtors showed. Also, the median existing-home price was $417,500, up 1.3% from a year earlier. 

“Despite the small monthly gain on a seasonally adjusted basis, August and September marked the two slowest months for home sales this year,” said Lawrence Yun, National Association of Realtors chief economist, in a press release.

“Further increases in mortgage rates in recent weeks mean fewer buyers can qualify to purchase a home.”

Related: Home Depot faces uphill battle amid a growing customer problem

Meta has quietly released Style Sketch, an AI fashion app that suggests outfits using clothes people already own. First spotted by social media consultant Matt Navarra, the app is available on iOS and Android in Indonesia, Singapore and Thailand. Meta did not respond to a request for comment, and it is unclear whether a wider release is planned.

The app connects to Instagram to build a virtual closet from users’ posted photos, or lets them add items by taking pictures, recording short videos or uploading images. It then recommends outfit combinations matched to each user’s style, which can be previewed on a realistic model reflecting their body shape and skin tone. Users can also pick a specific item to generate outfits around it, or enter a destination, trip length and activities to receive a day-by-day travel plan that factors in weather and itinerary.

Similar tools already exist, including startup Alta and features in Google Photos, so Meta’s edge will likely come from Instagram integration, where users already keep a visual record of their style.

Style Sketch joins a string of recent Meta AI apps, including Waddle World, Pocket and Vibes. CEO Mark Zuckerbergreportedly told employees that AI-driven efficiencies will let the company ship far more apps than before.

If you’re looking to build your retirement savings with an investment that offers passive income and long-term growth potential, the iShares S&P/TSX Composite High Dividend Index ETF (TSX: XEI) is certainly worth considering.

In fact, it currently offers an annual yield of roughly 3.4% and pays its distributions monthly.

However, what makes it appealing for retirement savings is that those payments can be useful whether you need the income today or are still years away from retiring.

Because while you’re building your portfolio, reinvesting those distributions allows you to accumulate additional units and increase the income your investments can generate over time. Then, once you retire, you can collect the cash to help cover your expenses.

So, here’s what makes XEI worth considering and why individual dividend stocks can still be useful alongside it.

Source: Getty Images

A Canadian dividend ETF to buy and hold for years

One of the biggest benefits of owning XEI is that it gives you exposure to roughly 75 Canadian dividend stocks without having to build that portfolio yourself.

However, how those investments are weighted is also important.

Its benchmark limits individual stocks to 5% and sectors to 30% at each quarterly rebalancing. That helps prevent one massive company or industry from taking up an increasingly large portion of your investment.

Financials and energy still account for roughly 60% of XEI’s portfolio, while utilities make up another 14%.

That primarily gives you exposure to businesses earning money from lending, transporting energy and supplying electricity, alongside producers that can benefit when commodity prices rise.

So, although XEI spreads your money across dozens of companies, its performance still depends heavily on those industries. That’s worth understanding when deciding how it fits alongside your other retirement investments.

Furthermore, the income it pays is only part of the return investors can earn.

For example, XEI generated a total return of roughly 29% from the beginning of the year through October 26, including reinvested distributions.

And while you obviously shouldn’t expect gains like that every year, it still demonstrates why the yield alone doesn’t tell you everything about what an investment can offer.

For retirement savings, that combination matters because you can collect income while continuing to own businesses with opportunities to expand their operations and increase their value over the long haul.

A higher-yield stock to own alongside your retirement ETF

While XEI offers a straightforward way to own Canadian dividend stocks, it doesn’t own every attractive income investment.

For example, Alaris Equity Partners (TSX: AD.UN) isn’t in its portfolio and currently offers a yield of roughly 6.7%, with quarterly distributions.

Alaris is an intriguing stock because it provides capital to established private businesses, primarily through preferred equity investments. That gives investors exposure to companies they generally couldn’t buy directly on the TSX.

Furthermore, those preferred investments generally pay Alaris distributions that are set for a year at a time and adjusted annually based on measures such as sales or gross profit.

So, its investments are structured to generate income while allowing that income to increase as those businesses grow. Plus, Alaris also owns common equity interests, allowing it to benefit from increases in those businesses’ value.

And Alaris isn’t solely dependent on the growth of its current investments. In fact, it’s continually looking for new businesses to invest in, giving it additional opportunities to grow its income.

Those recent investments helped drive a 41.8% year-over-year increase in net distributable cash flow in the second quarter, while its portfolio expanded to 25 partners.

More importantly, Alaris paid out only about 58% of its net distributable cash flow through the first half of the year, leaving cash available to strengthen and expand its business.

In fact, Alaris has already increased its distribution twice this year, giving investors growth in their income alongside its attractive starting yield.

So, while XEI and other high-quality dividend ETFs can provide a useful foundation for your retirement savings, Alaris is a good example of how the right individual stock can add exposure to businesses you couldn’t otherwise own while boosting your income over the long haul.

Amid persistent inflation and an uncertain macroeconomic environment, earning a steady passive income has become increasingly important for maintaining financial stability and preserving purchasing power. Investing in monthly-paying dividend stocks offers a convenient and cost-effective way to generate regular income and supplement existing earnings. However, dividend payments are not guaranteed, as they depend on a company’s financial performance, cash flow generation, and management decisions.

Therefore, investors should prioritize fundamentally strong companies with established businesses, predictable cash flows, a proven history of dividend payments, and sustainable growth prospects. Against this backdrop, I believe the following two monthly-paying dividend stocks present compelling opportunities for income-seeking investors. Investing $40,000, split equally between these two stocks, could generate more than $200 in monthly passive income. Moreover, holding these investments in a Tax-Free Savings Account (TFSA) would allow eligible Canadian investors to receive their dividends tax-free, provided they have sufficient contribution room.

COMPANYRECENT PRICENUMBER OF SHARESINVESTMENTDIVIDENDTOTAL PAYOUTFREQUENCYPEY$12.421,610$19,996.2$0.0699$112.54MonthlyAPR.UN$25.41787$19,997.67$0.12$94.44MonthlyTotal$206.98Monthly

Peyto Exploration & Development

Peyto Exploration & Development (TSX: PEY) is a Canadian energy producer with operations primarily concentrated in Alberta’s Deep Basin. Supported by its long-life reserves, low-cost operations, disciplined capital allocation, and operational efficiency, the company has demonstrated resilience across economic and commodity-price cycles. Its efficient operating model has delivered strong financial performance, with average returns on capital employed and equity of 17% and 24%, respectively, over the past 27 years.

Backed by consistent financial performance and healthy cash flow, Peyto has returned about $3.5 billion in dividends to shareholders since 1998. The company currently pays a monthly dividend of $0.12 per share, for a forward yield of 5.7%.

Meanwhile, Peyto continues to strengthen its production capabilities through strategic investments and infrastructure development. The company plans to invest $450 million to $550 million this year, focusing on drilling 70–80 net wells, expanding gathering infrastructure, and removing bottlenecks across its midstream operations. Furthermore, its substantial proved and probable reserves of approximately 1.5 billion barrels of oil equivalent provide a solid foundation for sustained production growth.

Supported by these expansion initiatives and its extensive reserve base, management targets annual production growth of 5% to 10% in the coming years. These investments, combined with ongoing operational improvements and disciplined cost management, could strengthen Peyto’s earnings and cash flows, enhancing its ability to sustain its monthly dividend payments. Given its attractive yield and encouraging growth prospects, I believe Peyto represents a compelling investment opportunity for income-seeking investors.

Automotive Properties REIT

Automotive Properties Real Estate Investment Trust (TSX: APR.UN) owns a portfolio of 95 commercial properties encompassing approximately 3.5 million square feet of gross leasable area. The REIT leases these properties to established automotive dealerships, original equipment manufacturers (OEMs), and automotive service providers under long-term agreements. Its high-quality tenant base and long-term leases support near-full occupancy, strong rent collection rates, and predictable cash flows. Furthermore, contractual rent escalations and consumer price index (CPI)-linked adjustments provide a hedge against inflation while supporting steady organic rental income growth.

Backed by its stable operating performance and reliable cash flow generation, Automotive Properties REIT has consistently rewarded unitholders with monthly distributions. It currently pays $0.07 per unit, translating into an attractive forward yield of 6.8%.

Meanwhile, the ongoing consolidation of the fragmented automotive dealership and service industries across Canada and the United States presents significant growth opportunities for the REIT. As automotive operators pursue acquisitions and expand, rising capital needs could drive demand for sale-and-leaseback transactions. These arrangements allow operators to unlock capital tied up in real estate while continuing to occupy their properties under long-term leases. This growing demand could create a robust pipeline of acquisition opportunities for Automotive Properties REIT, enabling it to expand its asset base and strengthen its recurring rental income.

With high occupancy rates, predictable cash flows, inflation-protected leases, and promising expansion opportunities, Automotive Properties REIT appears well positioned to sustain its monthly distributions. Given its attractive yield and favourable long-term growth prospects, I believe the REIT represents an excellent investment opportunity for income-seeking investors.

A Page Turner Made for Kindle

Page turners have been the latest item to have as an e-reader user, but while Kobo launched a remote last year, Kindle had yet to have one—until now.

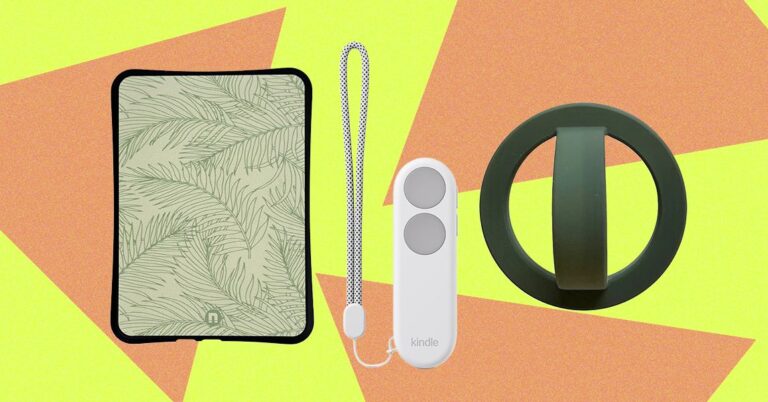
Kindle announced the release of the Kindle Click, its first Bluetooth page-turning remote, in early October, and it’s finally available to buy. It’s a huge improvement over third-party devices that required you to have one part of the device on your Kindle so it could tap and turn the page for you, and a remote in your hand. The worst part was not just that it blocked some of the screen, but that you had to track the battery life of two separate pieces.

The Kindle Click solves these complaints, and while it launched on the same date as the new Kindle Paperwhite and Kindle Colorsoft, it’s backward compatible with Kindle models from 2024. It’s easy to set up: Just go into your device settings, click on Wi-Fi and Bluetooth, and then Bluetooth devices to sync your Kindle Click. I tried it with both a 2024 Kindle and a 2026 Kindle Paperwhite Signature Edition, and both devices were able to find the Click almost instantly and start working.

The Click has two buttons on the main body that move forward and backward and will move around a page you’re on, too (but won’t select a book for you; it’ll just move through your library or homepage). There are also two buttons on the right side that let you adjust screen brightness, which is a fantastic convenience. There’s also an included lanyard to attach it to your wrist. It’s great to pair with a Kindle stand of any kind so you can prop up your Kindle and turn the page without lifting a finger.

Some Charger Options

If you’re getting a new Kindle, you might not be thrilled to discover you need to provide your own charging block to charge it. And if you haven’t already switched over your home’s collection of wall chargers to USB-C, you’ll be especially frustrated when you open the box and find only a USB-C cord. If you’re in the market for a new wall charger to pair with your Kindle, these are a couple of our favorites.

Anker

Nano 45W With USB-C Cable

This is our favorite wall charger for Androids and iPhones alike; it will work great for Kindles, too.

Stamish

USB-C Charger Block

I’ve had a collection of these charging blocks for a year and a half now, and they’re still going strong. I use them for everything from my family’s smartphones to my alarmingly large collection of e-readers.

Two Nvidia-backed technology giants are in talks to merge, a move that would create a $300 billion company. Marvell Technology MRVL is in talks to buy Lumentum (LITE), a company that focuses on optics that are used widely in the data center industry.

Visit Site

Marvell faces funding and valuation pressure if the optics deal closes.

51% of retail investor accounts lose money when trading CFDs with this provider.

According to Bloomberg, a deal to merge the two companies could be announced as soon as next week. The report warned that details were not yet finalized and that it could fall apart. 

This would be one of the biggest deals this year as Lumentum has a market capitalization of over $82 billion. An attractive deal would give it a big premium, meaning that the purchase price could be as high as $100 billion.

Lumentum’s business is booming as the data center build-up gains momentum. In a recent statement, the company said that its products were sold out through 2029. Analysts now expect that its annual revenue will jump by 110% this year to $6.3 billion, followed by $10 billion next year. Lumentum often does better than estimates, meaning that its real numbers will likely be better than that.

Marvell, on the other hand, has become a big partner to other companies in the tech industry like Google and Microsoft. It helps these companies build their chips, which then compete with those made by Nvidia and AMD. Analysts expect Marvell’s revenue to hit $12 billion this year and $20 billion next year. 

By buying Lumentum, Marvell aims to be the market leader in the optics industry. In other words, its products allow massive amounts of data to travel quickly and efficiently using light instead of traditional components. These products are in high demand as vast amounts of data are transferred in large data centers.

A deal to acquire Lumentum would face some challenges for Marvell Technology. First, Lumentum is not a cheap company. It has a forward price-to-earnings ratio of 40, much higher than other companies, including Micron and Nvidia.

Second, Marvell will need to give away a substantial portion of its stock and raise billions of dollars to fund the buyout. It ended the last quarter with less than $4 billion in cash and short-term investments. 

Further, there is a risk that the company is acquiring Lumentum at the peak of the AI boom. Indeed, the AI Stock Bubble Index has jumped to the highest level in months, and Ray Dalio and Ken Griffin are warning that it may burst soon.

In the past, M&A deals made at the peak of a cycle tend to face challenges. The most notable one is Teladoc’s purchase of Livongo Health at the peak of the pandemic. Teladoc had to announce a multi-billion-dollar impairment. 

Therefore, the deal would be good for LITE stock, and highly bearish for MRVL, at least in the immediate future.